Below, please find a special message from one of our advertisers

Blaze Sponsors
 

Below is a message from our sponsor, Allegiance Gold. 


Your Bank Changed You From
"Customer" To "Creditor"
Your deposit is legally a loan to the bank - it owns the cash, you own a promise. Washington rewrote the playbook: If the bank fails, it is now resolved with its creditors' money. Read the Terms

40 Years of Saving.
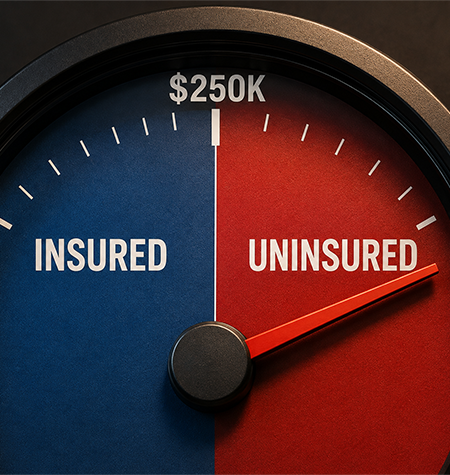
Only Part of It Is Insured.
Federal deposit insurance stops at $250,000 per depositor, per bank. Above that line, you're an unsecured creditor. A free 30-second calculator shows you how much sits above the line. Check My Exposure

They Showed Us Gold. But Not The Audit.
A U.S. senator walked through Fort Knox with cameras, and the matter was declared settled. But an audit answers what a tour can't: Is all the gold still there, pure, unpledged? Read More


Imagine discovering that the way you take your Required Minimum Distribution (RMD)

could influence your taxes, reinvestment strategy, and long-term retirement plan.

Each year, Americans over age 73 are required to withdraw more than $35 billion from their retirement accounts. Yet many retirees don’t realize that how they take their RMD may affect their overall financial strategy.

Most people take their RMD in cash because it’s the default—and often the only option their advisor mentions. However, withdrawing in cash may increase taxable income, reduce the amount that remains invested, and expose investors to market-timing challenges.

There's Another IRS-Approved Option

Many retirees are unaware that RMDs can also be taken “in-kind,” meaning you can receive certain assets—such as physical gold or silver—instead of taking the distribution in cash.

Taking an RMD in-kind does not eliminate taxes, but for some investors it may:

  • Help maintain their long-term allocation
  • Reduce the impact of selling assets during market volatility, and
  • Support diversification, depending on their overall plan

This IRS-allowed method is fully legitimate, though not commonly highlighted in traditional planning conversations.

Before Taking Your Next RMD, Consider:

  • Are you aware of all the IRS-approved ways to satisfy your distribution?
  • Could an in-kind RMD better support your diversification goals?
  • Are you unintentionally selling assets at a time that may not align with your strategy?

Understanding your options is essential.

This guide breaks down the differences so you can make an informed decision before taking your next withdrawal.


Allegiance Gold, LLC is not a broker-dealer and does not provide investment, tax, or legal advisory services. No statement in this communication should be construed as a recommendation to purchase or sell any security, or as investment, tax, or legal advice. Precious metals, like all investments, carry risk, are not suitable for all investors, and past performance does not guarantee future results. We do not guarantee any investment performance. Please consult your own investment, tax, or legal advisor prior to making any investment decision. Third-party information quoted or presented by us in this communication represents only the opinions of the third party and we do not endorse any third-party source of information. We are not affiliated with the U.S. Mint or any government agency. ©Allegiance Gold, LLC 2026


© 2026 Blaze Media LLC. All Rights Reserved.

You are receiving this email because you opted in to receive emails from Blaze Media. The advertiser may collect personal information based on your interaction with this email. Please read the advertiser’s privacy policy for more information.

Privacy Policy

8275 S. Eastern Ave, Ste 200-245
Las Vegas, Nevada, 89123, USA